While investors see deal opportunities returning across Asia, the next phase for private markets in the region signals a shift to fundamentals: greater selectivity and operational excellence.
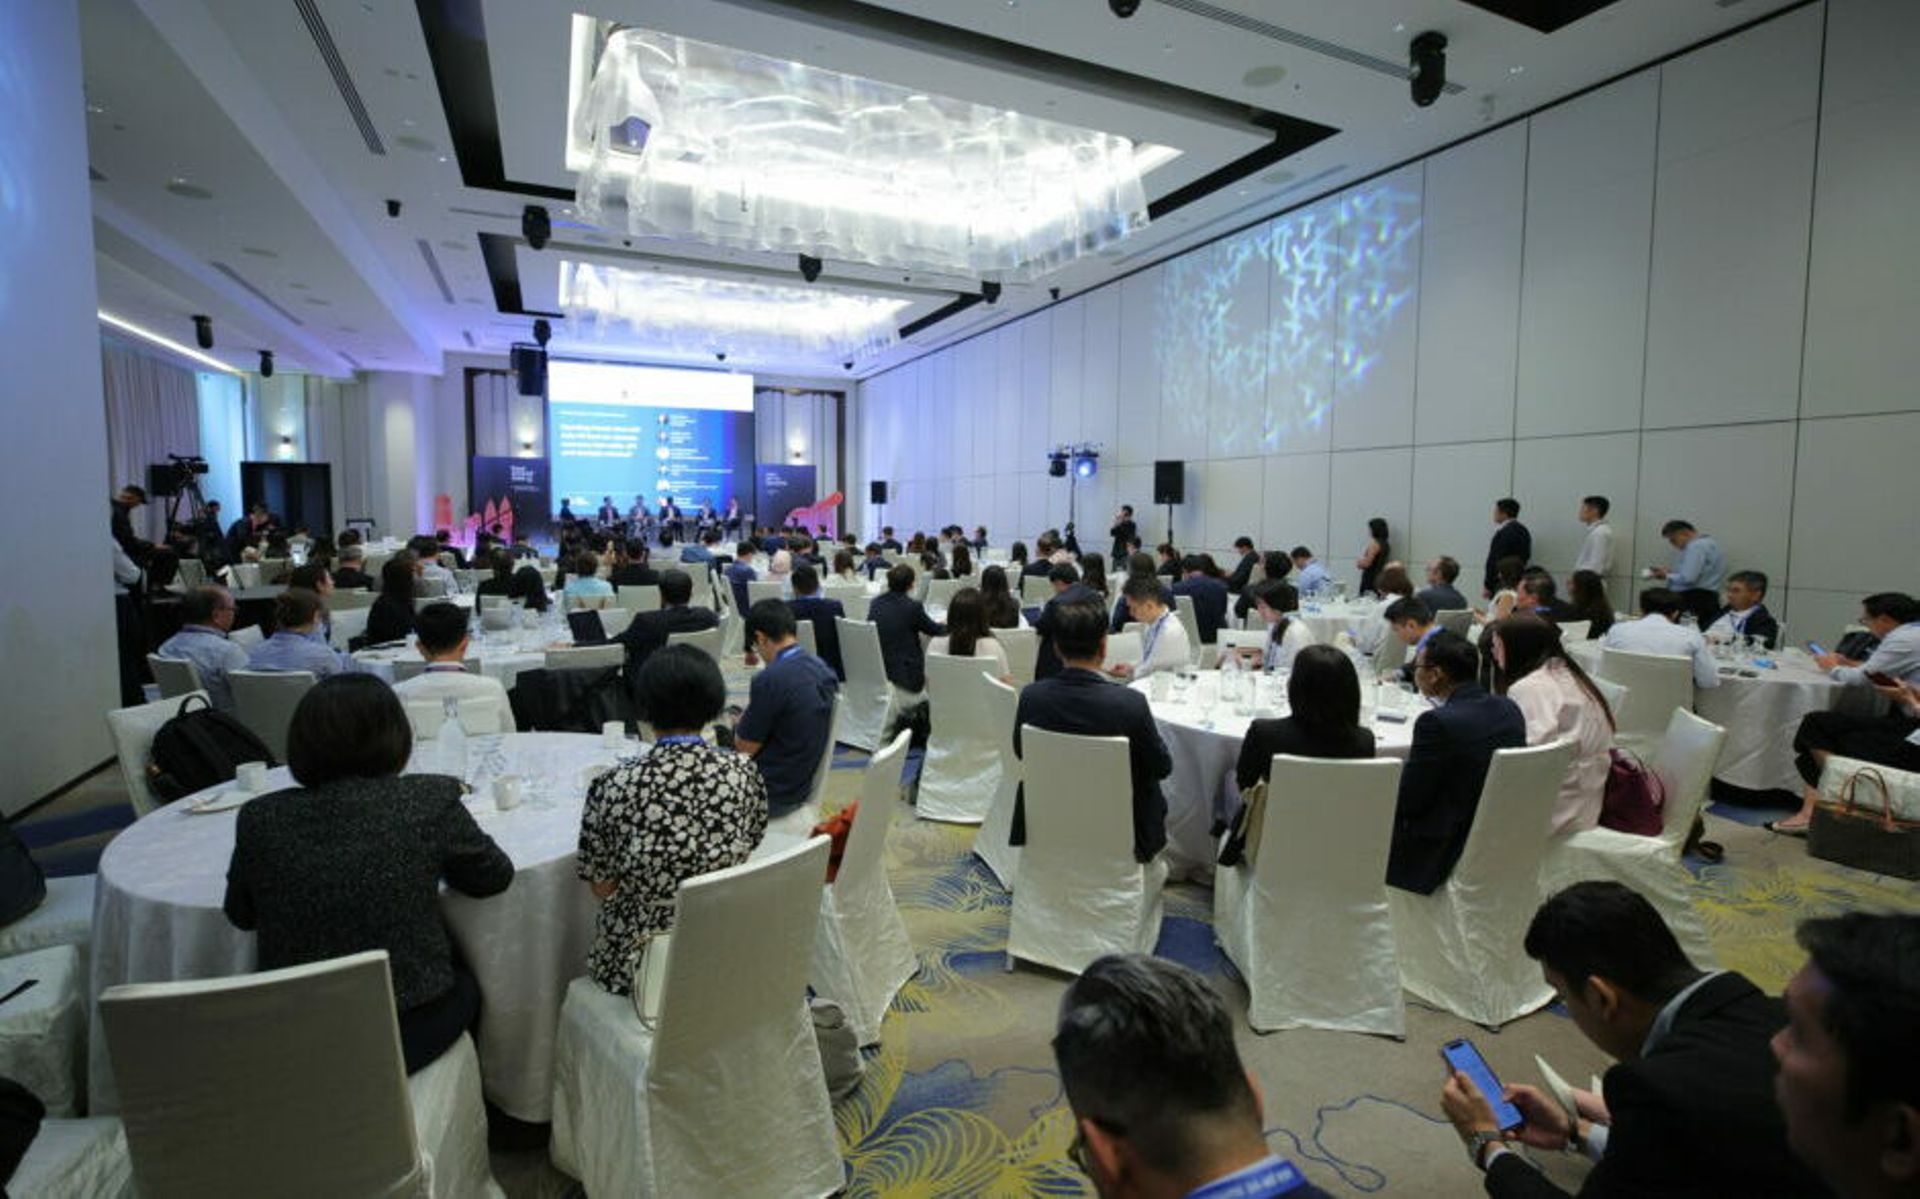
Asset allocators and fund managers, speaking at the Asia PE-VC Summit in Singapore on Wednesday, pointed out pockets of renewed opportunity from India and Japan to China and Southeast Asia, even as valuations, exit conditions and market fragmentation continue to shape investment decisions.
Across private equity, infrastructure and private credit, the emphasis is increasingly shifting from simply deploying capital to building businesses, structuring deals and creating clearer pathways to exits.
Here are the key takeaways from the Private Equity and Investment Summit:
Diverse markets, diverse sectors
India remains highly competitive and expensive but still has a long growth runway, while Japan is benefiting from corporate governance reform, take-private opportunities and private equity’s deeper penetration into corporate Japan.
Southeast Asia, meanwhile, is “not the flavour of the month” as exits remain difficult and scale can be harder to find across fragmented markets, Warburg Pincus head of Asia Private Equity and global co-head of Financial Services Vishal Mahadevia said. He described such shifts as “cycles and microclimates”, noting that India itself was once overlooked before becoming one of Asia’s hottest markets.
“Keep your head straight and keep a view for five years,” he observed.
From China, Johnson Huang, a director at CICC Capital’s PE team, identified neuroscience and brain tech, cell and gene therapy, and AI plus healthcare as attractive healthcare sub-sectors offering attractive risk-adjusted returns.
In terms of broader Asia opportunities, infrastructure took centre stage, with energy emerging as one of the biggest bets as rising electricity demand, the energy transition and the rapid buildout of data centres create a growing need for new power capacity. Exits in data centres, meanwhile, remain robust.
The broader message is that Asia’s infrastructure opportunity is expanding fast, but the next wave of returns will likely come from investors willing to build, structure and de-risk assets rather than simply buy capacity.
Becoming more disciplined
“It’s not about the macro. It’s about the micro.”
That is how Mahadevia framed the case for private equity in Asia, pointing to the region’s shift toward larger companies, bigger cheque sizes and more control transactions.
Executives from Bain Capital, Brookfield, and Blackstone also said they are tightening underwriting, prioritising control deals, and building exit plans from the outset to meet rising LP pressure on DPI.
While control opportunities are growing in China and broader Asia, experienced operational PE talent remains scarce and critical for deal execution, said Maggie Bian, a partner at HOPU Investments and ARM China’s COO.
With China’s private equity deal volume almost tripling and deal value surging 86% year-over-year in the first six months of 2026, panelists examined how this market has entered a phase of disciplined recovery and operational value creation.
PE dealmaking in China made a comeback without a proportional surge in available liquidity or GP fundraising, said Neuberger’s principal Yi Pan. “That in part gives me a little bit of comfort that this comeback is in a way disciplined. Because it is not liquidity-driven.”
India needs to sustain exits
India has long attracted private equity investors on the back of its strong demographics, economic growth and rising consumption. People are watching not only growth, but also factors like valuations, currency, exit opportunities and geopolitical diversification, stated panelists in a session titled ‘India PE has won the growth argument. Can it now return capital?’
With a deeper public market and PE fund managers having gone through several cycles of investments and exits. The market has matured over the years. According to Venture Intelligence data, India-focused PE-VC firms have encashed $13.52 billion so far this year, compared with $21.41 billion in 2025 and $26.31 billion in 2024, which clearly goes on to show that India has started delivering exits at scale.
But there is always scope for DPI to improve. In terms of valuation, it is still towards the higher side. Yet, investors are betting on the country, largely because of its long-term growth story.
While much of the conversation focuses on investments and exits, there is one crucial phase in between that deserves equal attention — value creation.
For PE firms, it is no longer just about buying the right business and finding the right time to exit. It is also about working closely with portfolio companies to improve performance, strengthen operations and build businesses that are worth more when it is time to exit.
All in all, it’s a market full of opportunity. There are plenty of companies to invest in. Exits have begun to pick up. Amid all this, it has become PE firms’ approach to value creation that will deliver better returns.
Shifting SE Asian PE exit landscape
Exits in SE Asia PE are shifting away from traditional auction processes, with sellers increasingly approaching strategic buyers for bilateral negotiations. IPO activity remains concentrated, making strategic M&A a more important route. Greater macroeconomic, policy and currency stability, alongside strong asset selection and clear equity stories, could help drive more deal activity and DPI.
For dealmakers, valuation gaps have narrowed, while multiple compression is creating opportunities for longer-term investors. In Indonesia, panelists highlighted strong fundamentals and long-term potential despite policy uncertainty and currency risks, which have led some investors to apply higher underwriting hurdles.
Credit market is not only about diversification
Asia’s private credit market, which started from a traditional focus on special situations, has grown into an important part of the private market landscape. Some markets in the region have developed deeper credit cultures, therefore offering sufficient scale to support different credit strategies.
That said, several global investors still approach Asia in an opportunity-driven manner rather than having a systematic view. Even as these investors are trying to seek diversification, they need to have a top-down view of how diversification is formed to deliver returns.
Structural challenges to scaling private credit remain in the fragmentation of the market and each country’s banking regulation. Some other factors such as FX, illiquidity, and enforcement risk also weigh on deals, with some of these risks difficult to price accurately.
This places a premium on managers with strong local expertise, disciplined underwriting and carefully structured deals, alongside partnerships with other stakeholders, including banks.
Despite these challenges, the growing depth and breadth of Asia’s private credit opportunity, with greater sophistication in deal structures and market infrastructure, is expected to support the asset class’s continued development.