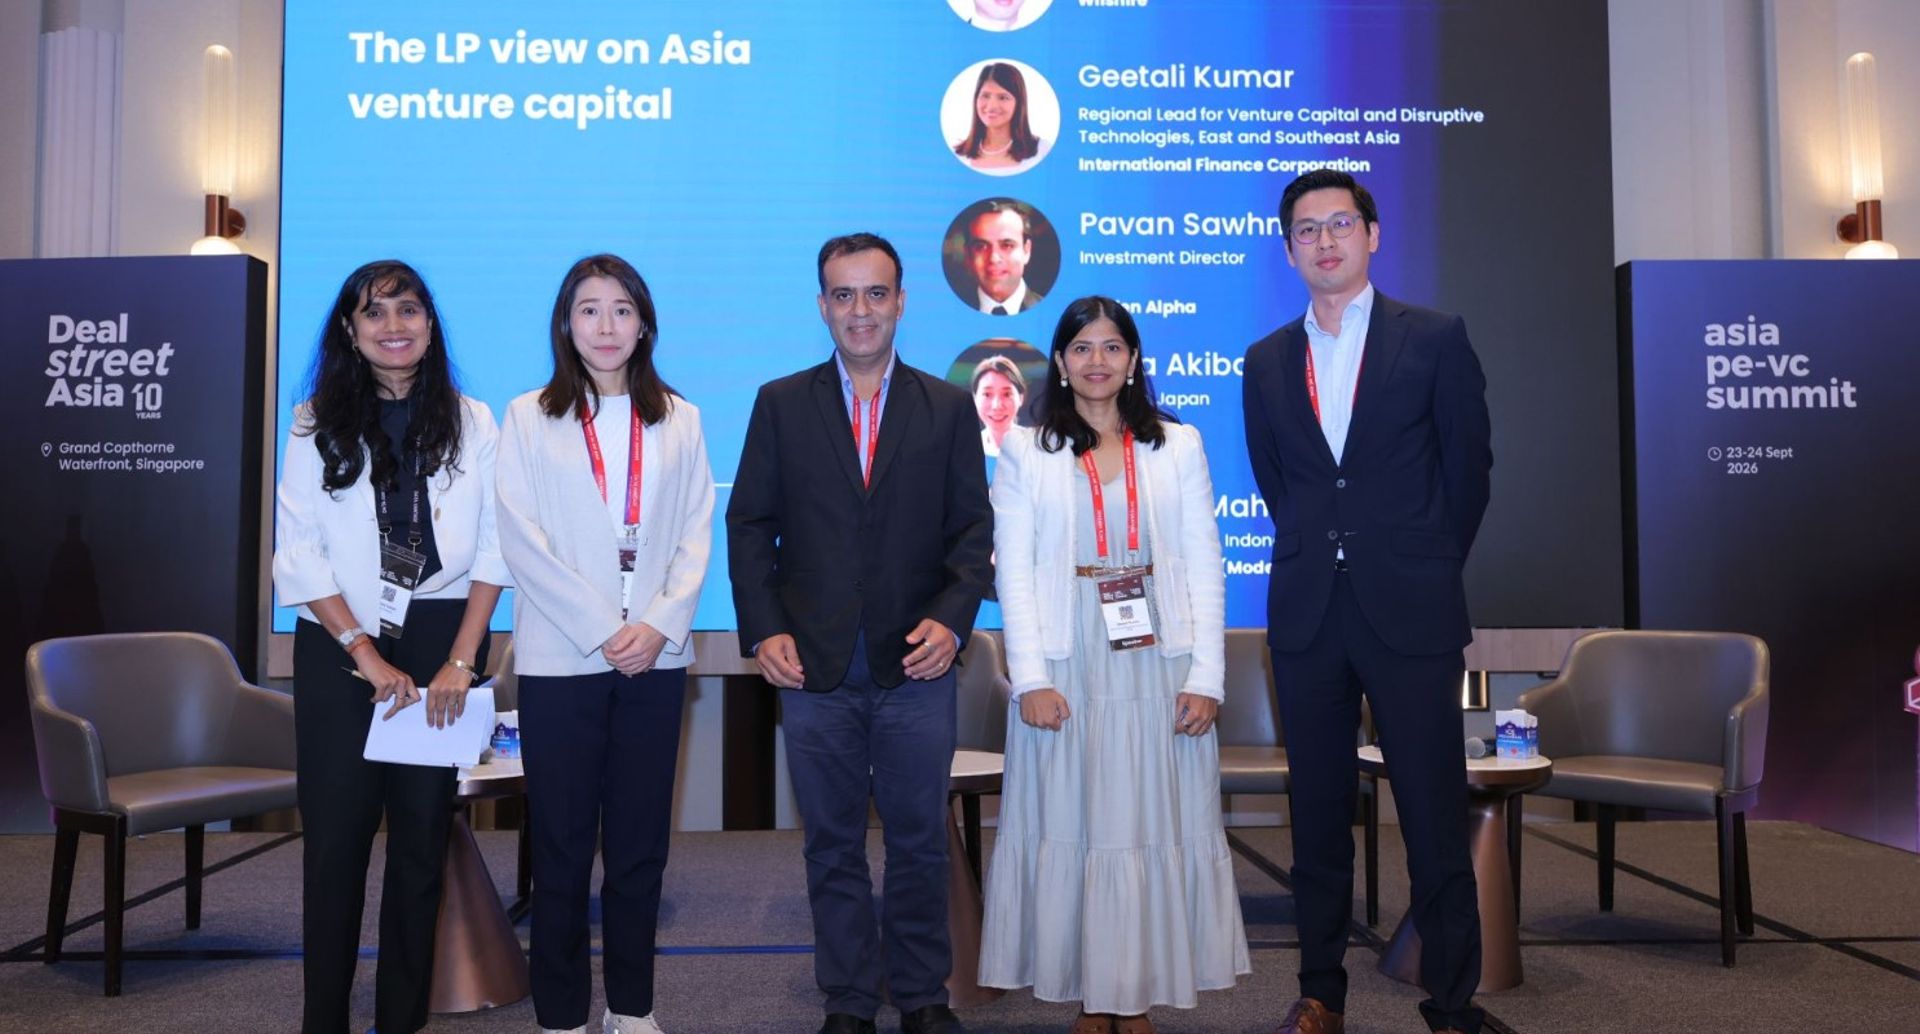
Institutional and family office investors are becoming more selective about Asian venture capital allocations as limited partners place greater emphasis on returns, valuations and exit prospects, according to panellists at DealStreetAsia’s Asia PE-VC Summit 2026 in Singapore last week.
Allocators said Asia remains relevant to global portfolios, but they are increasingly assessing individual markets, sectors and fund managers rather than treating the region as a single investment opportunity.
“For Asia venture, we tend to look at country-focused funds because we do see that each of the markets is very different,” said Gary Hui, senior vice president and head of the Hong Kong office at investment consultant Wilshire.
Wilshire continues to maintain an Asia venture allocation for some clients, partly because the correlation between US and Asian venture markets is declining, Hui said.
Within Asia, however, the firm applies different approaches to markets including China, Southeast Asia, Japan and South Korea.
For Singapore-based single-family office Golden Alpha, Asian venture has struggled to compete with opportunities in US technology in recent years.
“We’re purely seeking returns. When we look at returns from the US and public markets, it’s very hard for Asian venture to compete right now,” said Pavan Sawhney, investment director at Golden Alpha.
The family office has largely stayed away from Asian venture in the past few years, although it is examining selective opportunities in India and Southeast Asia, Sawhney said.
Investors said the return of capital to LPs will be critical for the recovery of Southeast Asia’s venture market after several difficult years.
“The moment DPI comes back, you know everybody’s interested in the market again,” said Geetali Kumar, regional lead for venture capital and disruptive technologies at the International Finance Corporation.
Kumar said the region’s fundamentals remain intact, including its population, Internet penetration and opportunities for technology companies, but a stronger exit market is needed to bring investors back.
“Asia accounts for about a third of our global portfolio. Given the region’s scale and population, we are long-term investors, with exposure across India, China, South Asia and Southeast Asia,” she stressed.
She said investors should look beyond the number of initial public offerings and assess whether companies can sustain their performance after listing.
“It’s not just about the listing. Does the stock hold up afterwards, right? Six months later?” Kumar said.
Sawhney said a recovery would need to be demonstrated through multiple exits rather than a handful of successful transactions.
“Obviously exits, but then not just one exit, but a number of exits to prove that the model is repeatable,” he said.
Saya Akiba, director for Japan at Allocator One, said higher merger and acquisition activity and corporate venture capital participation could also signal a strengthening ecosystem.
China was another area where investors said allocations were becoming more targeted, particularly towards artificial intelligence, robotics and other technology sectors.
“We have never shied away from China, despite geopolitical risks… some of our investments have already reached IPOs and generated DPI. We also look at Japan VC for its relatively high DPI,” Hui said.
Sawhney said Golden Alpha was also examining Chinese venture opportunities, but would focus on specialist managers rather than broad-based funds.
“It’s definitely going to be a lot more selective,” he said. “If there are specialist funds with a track record in that, they will be considered.”
He said lower Chinese venture valuations were also prompting the family office to examine whether the market could offer opportunities over the longer term.
Japan offers a different proposition, with Hui pointing to opportunities in AI and robotics as the country responds to an ageing population and shrinking workforce.
Diversification matters
Despite competition from US technology investments, diversification remains an important reason for some LPs to maintain exposure to Asia.
“You cannot have 100% sitting in US AI companies,” Sawhney said. “As much as it would be great returns, 100% sitting in US AI companies is not prudent portfolio management.”
Hui said opportunities also differ significantly between markets. “We do see that in the US and in Asia, the opportunities are very different. Even for AI, US, and China, the winners are very different,” he said.
For Allocator One, geography is not itself a reason to back an Asian manager. Akiba said the firm assesses emerging managers globally using the same framework.
“We didn’t pick them because they’re Asian. We picked them because they’re good emerging managers,” she said.
Akiba said Allocator One has invested in seven Asian VC funds among more than 24 emerging-manager investments.
Panellists said the tougher fundraising environment had also increased LP bargaining power, with some investors able to negotiate management fees, co-investment rights and side-letter provisions.
At the same time, emerging managers without established fund track records face a high bar. Akiba said previous entrepreneurial or investment experience can be considered, while Hui said portfolio construction remains important.
Sawhney said managers should also be realistic in their fundraising pitches.
“Overpromise and underdeliver,” he said, when asked about a common mistake by Asian VCs. “The advice would be to underpromise and overdeliver.”
Kumar said venture capital should be viewed over a much longer timeframe.
“VC funds should be a 10-year horizon,” she said. “It’s a much longer horizon.”