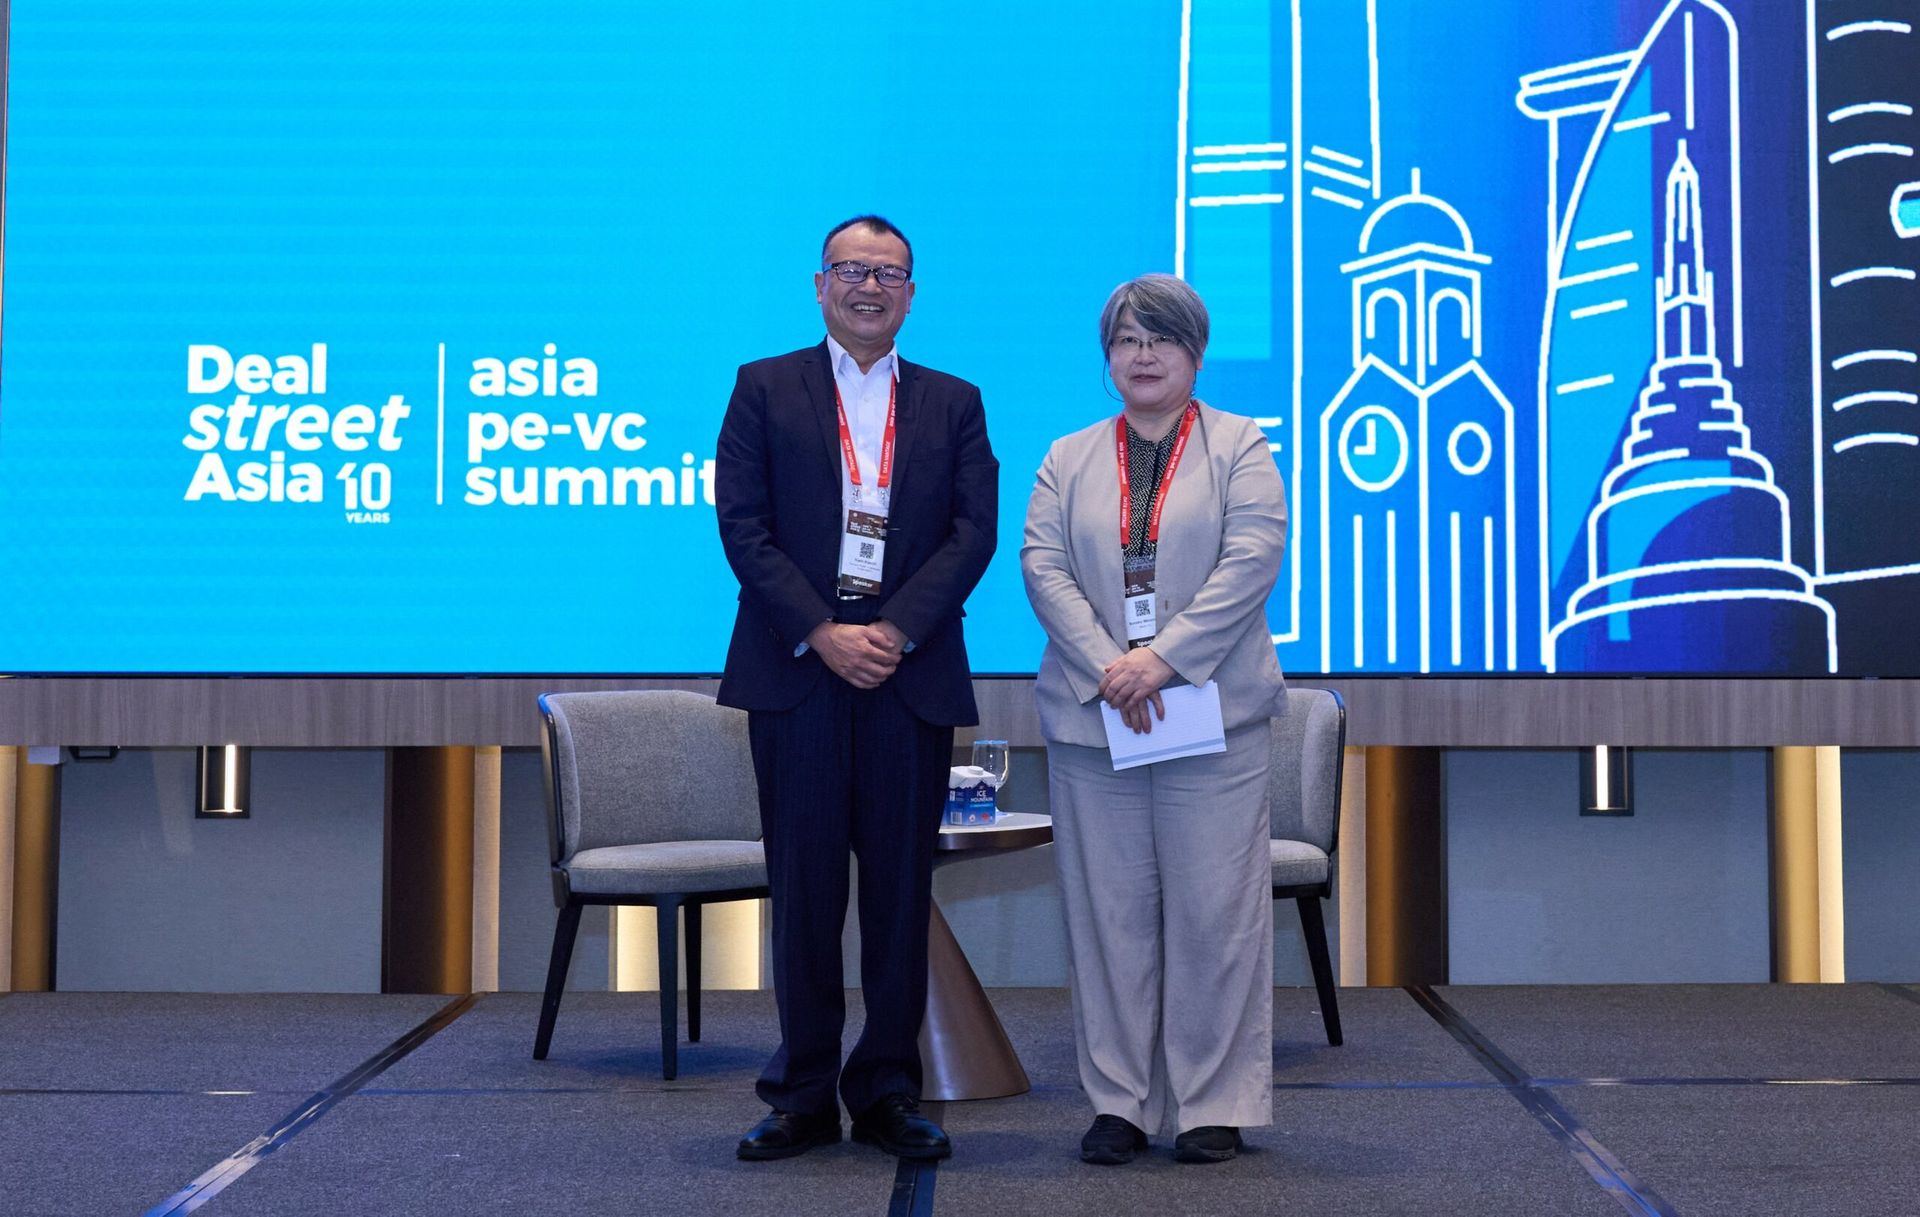
Pension Fund of Japanese Corporations (PFJC) is looking to gradually increase its allocations to several Asian markets, according to Yoshi Kiguchi, the fund’s Chief Investment Officer.
India, Southeast Asia and even China are on the fund’s radar, Kiguchi said, speaking during a fireside chat session at the Asia PE-VC Summit 2026.
PFJC is sponsored by around 1,300 small and mid-sized Japanese corporations, making it a relatively new concept in Japan’s pension market.
“Our revenue is growing about 40% annually. We can take more risks [in private markets], and we’re focused on long-term investments,” he said.
Kiguchi, who began his private equity career nearly four decades ago when the market was still in its infancy and accounting standards were less developed, said he has seen private markets become increasingly sophisticated outside the US over time, including across Asia. “So, we have more confidence in the Asian market.”
The shift comes as Japanese institutional investors seek higher returns from private asset classes. For decades, capital preservation has been a central priority, but Kiguchi said that conservative approach is no longer sufficient to protect the real value of pension assets.
“We have to change,” he observed.
Additionally, Japanese pensions have also historically maintained a strong home-market bias, despite relatively low domestic growth rates. This is prompting investors to look overseas for markets with stronger growth prospects.
“We have to find appropriate growth areas. Corporate pensions’ domestic investments have become much smaller. For our fund, our investments are 100% overseas,” Kiguchi said.
The shift could create a significant pool of capital for global private market managers. Japanese corporate pension funds generally have around 20% of their assets under management allocated to alternative investments, which Kiguchi said is relatively high compared with other institutional investors.
For example, GPIF had only 1.74% invested in alternatives in its 2025 fiscal year, with a cap of 5%, while the Pension Fund Association reported that 9.1% of its fund sits in private equity. Japan Post Bank saw around 6% of its assets in private markets last year.
“We believe we are now more sophisticated. We are increasing diversification into private assets.”
For other Japanese LPs with a smaller percentage of alternative investments, even a 1% change in allocation can translate into tens of billions of dollars.
However, global managers seeking to tap Japanese institutional capital should also be mindful of the market’s preferences around fund track records and distributions. Japanese LPs tend to be cautious about investing in first-time funds, according to Kiguchi, in part because cash distributions are particularly important to them and are easier to assess once a manager has established a track record across multiple funds.
“Your IRR might be strong, but the most important thing is cash return,” he said.
For emerging managers, he added, having a clear point of differentiation is critical. But more importantly, Japanese LPs want to see their ability to deliver on that differentiation.