Alternative investments are becoming an increasingly important part of wealth clients’ portfolios, particularly as Hong Kong strengthens its position as a global wealth hub. Yet private banks have been slow to fully capitalise on the opportunity.
Alternatives are the second most prominent investment theme among clients, according to the Hong Kong Private Wealth Management Report 2026, published by the Private Wealth Management Association and KPMG China.
However, none of the asset managers and fund houses surveyed believes that private banks are making full use of the opportunities in this space. The findings point to room for closer cooperation between product providers and private banks, particularly in developing suitable offerings, educating clients and integrating alternatives into portfolio strategies.
A similar disconnect is emerging in digital assets. Although the range of available products is expanding, nearly all surveyed firms said allocations still account for less than 5% of their Hong Kong assets under management. Greater client education, more robust portfolio advice, liquidity planning and governance frameworks will be needed to turn growing product availability into meaningful investment activity.
Tokenisation could eventually broaden the range of private and real assets accessible through wealth advisers. However, its wider application will depend on progress in secondary-market liquidity, interoperability between platforms and consistent valuation practices.
Meanwhile, the next generation of wealth holders is becoming an increasingly important client segment, with 91% of surveyed firms saying they have stepped up their focus on this group.
“These are a different kind of client. They are younger, often still running their companies, and some wealth is still tied up in a private business. They understand risk, know venture and private markets well, and care more about the next opportunity than about preserving the last one,” said Hong Kong Financial Secretary Paul Chan.
However, data and talent capabilities have not kept pace with this shift.
Only 58% of firms said they were able to recruit sufficient qualified professionals, while client information at most institutions remains fragmented across systems or siloed.
These constraints are closely linked, the report pointed out. Serving the next-generation requires firms to connect information across relationships, entities, portfolios and life stages, and to bring in specialists when succession, governance, philanthropy, mobility or long-term portfolio questions arise.
A growing industry
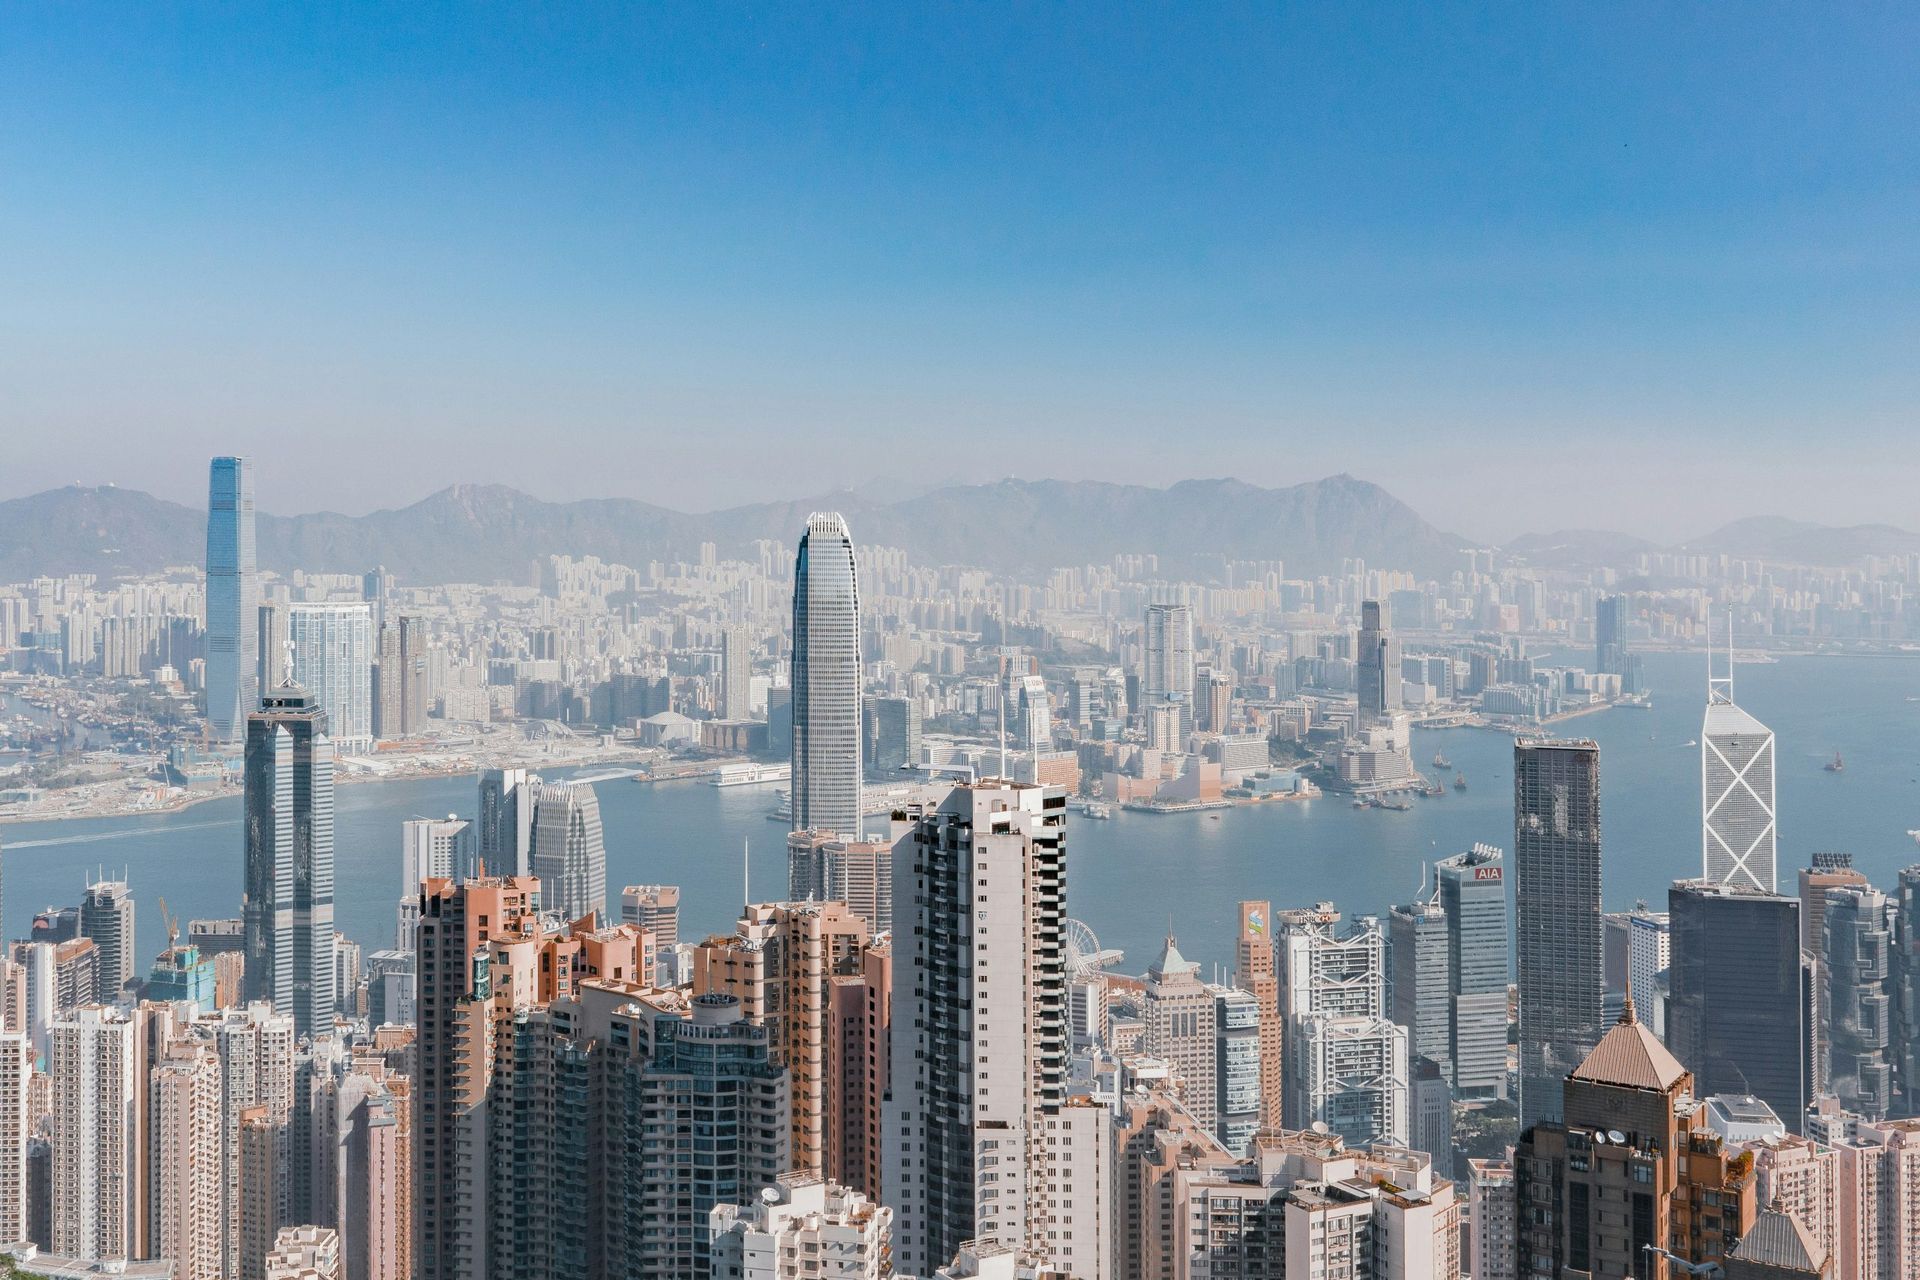
Hong Kong’s wealth management industry continued to expand in 2025, with assets under management rising 24% year-on-year to more than HK$12.9 trillion ($1.6 trillion), the highest level in a decade.
The increase was underpinned by strong net inflows, rather than on asset appreciation alone. Net fund inflows climbed 79% to HK$686 billion over the year.
Demand for Hong Kong as a booking centre also gained momentum, with 77% of surveyed firms reporting increased enquiries or demand for accounts and asset booking in the city, compared with 59% a year earlier.
While mainland China is expected to remain the industry’s largest source of assets, wealth managers are increasingly looking beyond the mainland, with Southeast Asia, Europe and the Middle East emerging as potential markets for expansion.
However, translating interest from these regions into actual assets will require considerable investment. Unlike the mainland market, where cultural familiarity and geographic proximity offer natural advantages, winning clients in more distant markets requires firms to build their presence from the ground up.
Despite geopolitical uncertainties, confidence in the city’s longer-term prospects remains high. Some 94% of surveyed firms expressed moderate or strong optimism about Hong Kong’s position as a private wealth management centre over the next five years.
The report suggests that geopolitical developments may be receiving disproportionate attention relative to their impact on underlying economic activity. Trade and wealth flows across Asia, it argues, continue to be driven by economic fundamentals, which remain robust.